- For beginners: A reputable hot wallet may be the easiest place to start, especially if you want simple buying, sending, and receiving
- For long-term holders: A cold wallet can make sense if your main goal is to reduce online exposure and you do not need constant access
- For active users: Some people keep a hot wallet for everyday transactions and a cold wallet for assets they do not plan to move often
If you own cryptocurrency, choosing a wallet is one of the most important decisions you can make.
The right wallet affects how easily you can send, receive, and store assets, but it also affects how much control you have over your funds and how exposed you are to risk.
→ SocialGood - Crypto Rewards for Shopping - CPS (US) {Mobile} — free, takes about 60 seconds.
For many people, the best choice is not the most advanced option — it is the one that matches how they actually use crypto.
Start with the two main wallet types
Most people will choose between a hot wallet and a cold wallet . The difference is simple: hot wallets stay connected to the internet, while cold wallets are designed to keep private keys offline or away from regular online use.
Hot wallets
We go deeper on this in how crypto actually works — worth a read before you decide anything.
Hot wallets are usually apps, browser extensions, or exchange-linked wallets. They are convenient for frequent transfers, small balances, and interacting with crypto services.
Because they are online, they tend to be easier to set up and use, but that convenience comes with more exposure to phishing, malware, and account compromise.
→ See what you could be approved for — free, takes about 60 seconds.
Cold wallets
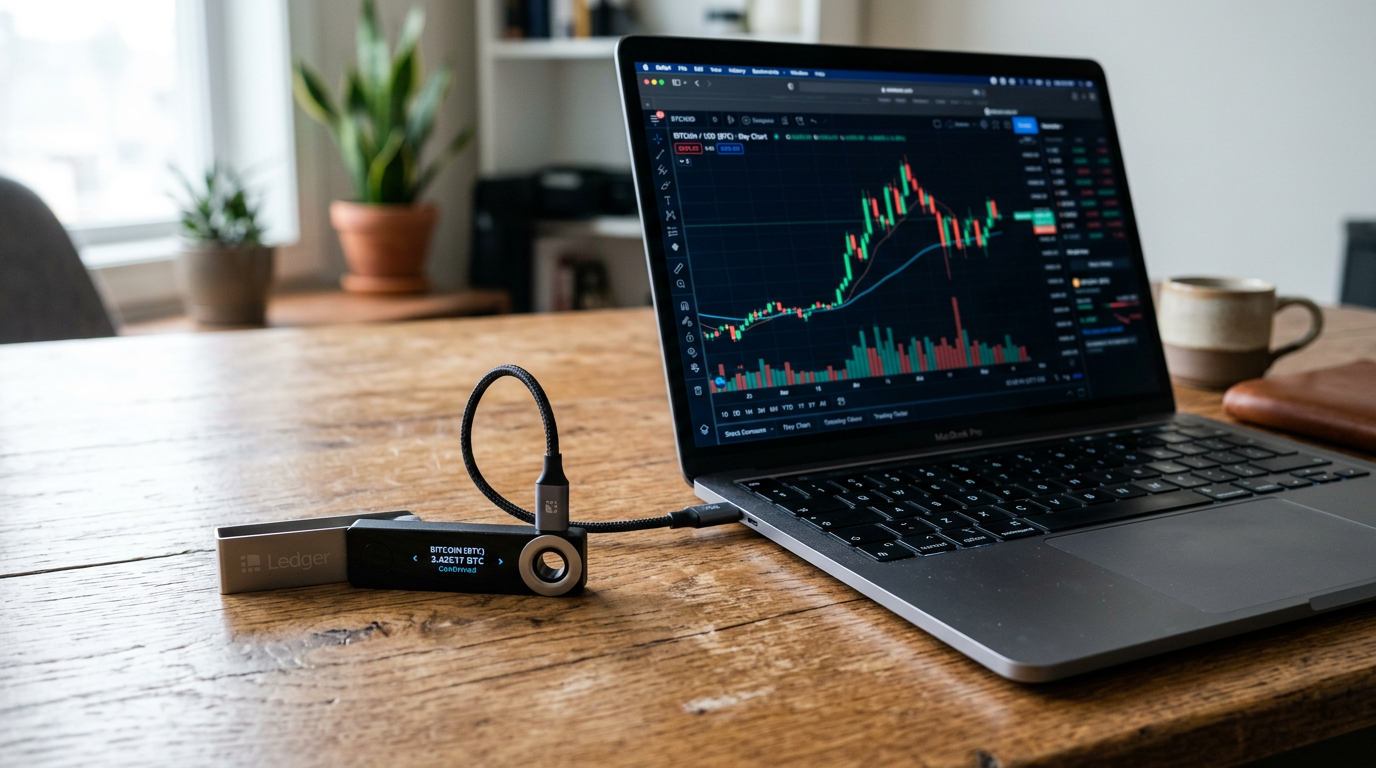
Cold wallets, especially hardware wallets, are built for stronger long-term protection. They are commonly used by people who want to store larger balances or keep funds away from daily internet exposure.
The tradeoff is that they can be less convenient, and you need to be careful about backups, recovery phrases, and device security.
Sources & further reading
- Consumer Financial Protection Bureau (CFPB)
- Federal Trade Commission — Credit & Debt
- MyMoney.gov — U.S. Financial Literacy
- Internal Revenue Service (IRS)
This article is for general information only and is not professional financial, legal, or medical advice.
Dana Whitfield — Personal Finance Editor
Dana has spent more than a decade writing about consumer debt, credit, and everyday money decisions, translating dense policy and lender fine print into plain-English steps readers can actually use. Every figure here is checked against current federal and lender guidance.
✓ Reviewed for accuracy by Marcus Reed, Accredited Financial Counselor · Updated August 2026

No comments:
Post a Comment